The opinions expressed below are my own and do not necessarily represent those of Visdom Investment Group, LLC.
Turning point?
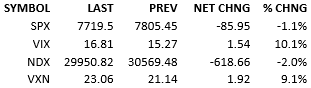
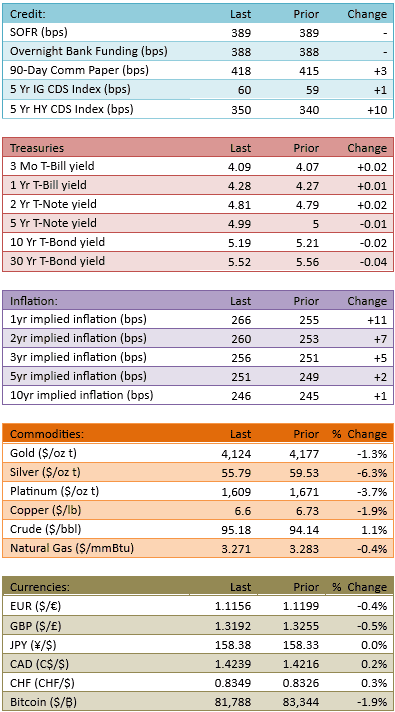
A modest risk-on behavior was in effect this morning but hot CPI data (+3.7% vs +3.6% est & 3.4% prior) changed everything. S&P futures dropped and yields popped. Six S&P 500 stocks also reported their earnings this morning too and their results were received about the same as yesterday’s reporting stocks, which isn’t great. The S&P opened down about 30 points and declined further, in a fairly calm trend, over the rest of the day. Yields began the day much higher across the curve but settled down and finished with slight increases on the front and slight drops on the back. Crude continues to climb, albeit slightly.
Hotter-than-expected inflation was certainly a surprise this morning. This refocuses Street attention on a hiking cycle from the Fed. For a week or two, the market narrative surrounding the Fed had slowly changed from a true hiking cycle through 2027 to a chance that the Fed would only hike one more time in 2026 and then sit tight for a while. That narrative shift certainly helped the bulls lately but now it’s become wishful thinking.
October hiking probabilities were 20% yesterday, 50% after this morning’s CPI, and 33% by the close. Obviously the market is moving around a lot and not sure what is likely to happen October 28. That’s OK though. For us, the takeaway is not the actual probability, it is the fact that is so wildly changed. That’s our evidence that the previous dovish narrative in the market has been damaged. Who knows what the new narrative will be or should be… but the old one is wrong and should be discarded by us.
From a Fed-perception standpoint, today was a turning point.
Let’s talk about earnings season too. Usually the start of earnings season brings excitement, usually the bullish kind. So far, we’re lacking that. At best, one can characterize the market’s mood as indifferent. At worst, one could call it disappointed. Here are today’s results:
6 S&P 500 stocks reported today
Stock return:
Beta-adjusted:
Let’s just call this lackluster. For the last few months, a common bullish rationale was the coming strength of earnings. The anticipated earnings growth was so great that it justified not just existing valuations but also bullishness in the face of higher interest rates. From a top-down standpoint, this isn’t wrong either. S&P earnings next year are expected to grow 28%. They are expected to grow another 16% the subsequent year. Much of that growth is due to mega cap tech and the AI investment space.
I don’t know whether that growth is currently at risk, but I certainly don’t take comfort in the fact that reporting stocks so far, are not impressing investors. I would prefer to see these “other” stocks reporting strong results and delivering strong returns. Maybe they don’t need to. Maybe mega cap tech can do it all on their own. I don’t like that but it’s possible.
From an earnings standpoint, is this another turning point?
See you tomorrow.
-Mike
Visdom Market Commentary
IMPORTANT INFORMATION
This is general educational information and market commentary and is intended for informational purposes only and is not intended as an offer or solicitation for the purchase or sale of any financial instrument or as an official confirmation of any transaction.
All market and economic data herein is as of the date hereof and sourced from Bloomberg unless otherwise stated. The information is subject to change without notice and we have no obligation to update you.
This general market commentary is intended for informational purposes only and is not intended as an offer or solicitation for the purchase or sale of any financial instrument or as an official confirmation of any transaction. The views and opinions expressed constitute the author(s) judgment based on current market conditions, are subject to change without notice, and may differ from those expressed by other employees of Visdom Investment Group LLC ("Visdom") and Visdom. Past performance and any forward-looking statements are not guarantees of future results. It is not possible to invest directly in an index.
We believe the information contained in this material to be reliable and have sought to take reasonable care in its preparation; however, we do not represent or warrant its accuracy, reliability or completeness, or accept any liability for any loss or damage (whether direct or indirect) arising out of the use of all or any part of this material. Any securities referenced are shown for illustrative purposes only, and are not intended as a recommendation or endorsement by Visdom or by the author(s) in this context. The information presented is not intended to be making value judgments on the preferred outcome of any government decision. This information does not constitute Visdom research, nor should it be considered a recommendation of a particular investment strategy or an offer or solicitation for the purchase or sale of any financial instrument. Investing involves market risk, including the possible loss of principal. You should speak to your financial advisor before making any investment decisions. Visdom and its affiliates do not provide legal, tax or account advice so you should seek professional guidance if you have questions.
